Debt keeping you up at night?
There is a way out from under this. Let's find yours.
Talk to Sandy right now — out loud, in your own words. No forms, no judgement, no waiting for office hours. She'll answer your questions and book a free call-back from a registered debt counsellor.
- ✓ Free and confidential
- ✓ NCR-registered · NCRDC0000 (demo)
- ✓ Based in Durban, helping all of South Africa
Sandy
Available now
Hi, I'm Sandy. Tell me what's going on, in your own words. What's worrying you most?
Sandy is an AI assistant. A human counsellor calls you back.
Start where it hurts
What's keeping you up?
Tap the one that sounds like you. Sandy will already know why you're here — you won't have to explain it twice.
The solution
What changes when you go under debt review
Debt review is a legal process under the National Credit Act. It gives you breathing room, protects what you've worked for, and turns many payments into one you can actually manage.
One affordable payment
All your accounts become one monthly amount that leaves you enough to live on.
The calls stop coming to you
Once you are under debt review, your creditors deal with us — not with you.
Protect your home and car
Debt review can stop legal action on your bond or vehicle, if you apply in time.
Pay less each month
We negotiate lower instalments and interest on your behalf. Every case is assessed individually.
See the difference
What would be left for groceries, taxi fare and school?
Move the sliders. Nothing is saved and nobody sees this but you.
Left over today
R8 500
Before food, transport, rent.
Could be left over
R11 350 – R13 250
With one restructured payment.
An illustration, not a quote. Your real instalment depends on your budget and on what your creditors agree to. A registered counsellor works it out with you — free.
How it works
Six steps. We do the hard ones.
- 1Talk to usSandy or one of our counsellors listens, day or night. Free and confidential.
- 2We assess your budgetYour income, your living costs, and what you really owe.
- 3We tell your creditorsThey are formally notified that you have applied for debt review.
- 4We negotiate for youLower instalments, lower interest, longer terms — a plan you can afford.
- 5One payment a monthYou pay one amount. It is distributed to every creditor for you.
- 6ClearanceWhen the debts in the plan are paid, you receive your clearance certificate.
From 2am to a plan
“I called at quarter past one in the morning. By nine, a counsellor had phoned me back.”
Example story · placeholder until real, consented client stories are supplied
01:14
Talks to Sandy about a Section 129 letter on her car.
08:05
Counsellor calls back. Budget assessed on the phone.
11:30
Payslips and statements uploaded from her phone.
Client stories
They were where you are now
“I sleep through the night again”
I phoned at one in the morning because I couldn't stop crying about a letter from the bank. Sandy listened, and a counsellor called me at eight. Fourteen months later my car is still in my driveway and I sleep through the night.
“Two accounts paid off — I can see the end”
Six creditors, six debit orders, nothing left for groceries. Now it's one payment, and the app shows me exactly how much is left. Two accounts are already paid off. My kids noticed I stopped shouting about money.
“Nobody judged me”
I was so ashamed I didn't tell my husband for a year. The counsellor never once made me feel stupid. They explained every fee before I signed anything, and the creditors stopped phoning me at work.
Demo website: example stories, invented to show the layout.
Questions people ask us
The things you're afraid to ask
Will I lose my house or car if I go under debt review?
Debt review cannot make you lose your home or car. It can often protect them, but that depends on timing — whether you have had a Section 129 letter, and whether a summons has been served. Talk to us as soon as a letter arrives.
How long will I be under debt review?
Usually three to five years, depending on what you owe and what you can afford. Your counsellor shows you the expected term before you commit.
Do I have to go to court?
No. We handle the application. You do not need to appear in person.
Will I be blacklisted?
A debt review flag is placed on your credit record while you are in the process. It is removed when you receive your clearance certificate.
Can I take out new credit while under debt review?
No. That is part of what protects you — no new debt while the existing debt is being repaid.
Do I have to visit your office?
No. You can do everything by phone, WhatsApp and this website, including sending your documents. You are welcome to visit our Durban office if you prefer.
Will my creditors still contact me?
Once you are under debt review, your creditors must deal with us. If one calls you, give them our number.
What if a creditor calls me anyway?
Tell them you are under debt review and give them our details. Let us know and we will take it up with them.
Can I apply if I am unemployed?
Debt review needs an income to build a repayment plan. If you have lost your job, talk to us anyway — we will tell you honestly what your options are.
Will my employer find out?
Not from us. Your employer is only involved if a garnishee order is already in place.
What does debt review cost?
Fees are set by the National Credit Regulator's guidelines and are built into your monthly payment. Your counsellor explains every fee before you sign anything. Talking to us costs nothing.
What if I cannot pay my instalment one month?
Call us before it happens. Missing a payment can put the process at risk, and there is often something we can do if we know early.
Are my insurance policies affected?
Your insurance stays in place and is included in your budget. Keeping cover for credit-linked items is usually required.
Your question isn't here?
Visit us
Three offices across Durban
Prefer to talk face to face? Pop in — no appointment needed in office hours. Or do everything by phone and this website.
- Demo offices for an invented practice. Phone 031 000 0000 · or talk to Sandy, any time.
The first step is just a conversation.
Sandy is here now. Tell her what's happening, and a registered counsellor will call you at a time that suits you.
Are you a debt counsellor? This website can be yours.
Everything you've just seen — Sandy, the client portal and the CRM behind it — is a ready-to-trade system for South African debt counselling practices. Your name, your logo colours, your offices and your NCR number.
- ✓Sandy books call-backs while your office is closed
- ✓Clients track their own progress and keep paying
- ✓A CRM built for debt review, connected to your dialler
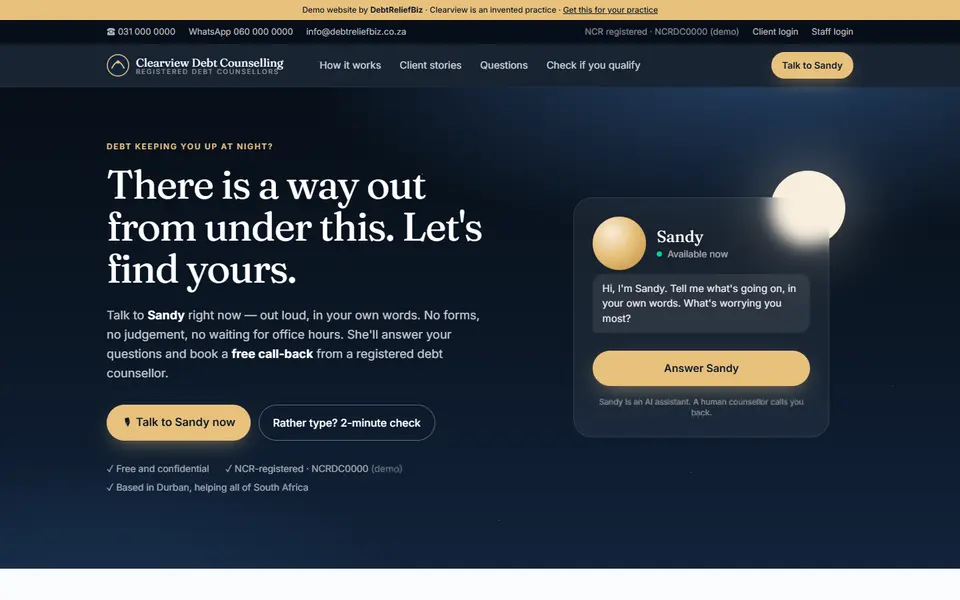
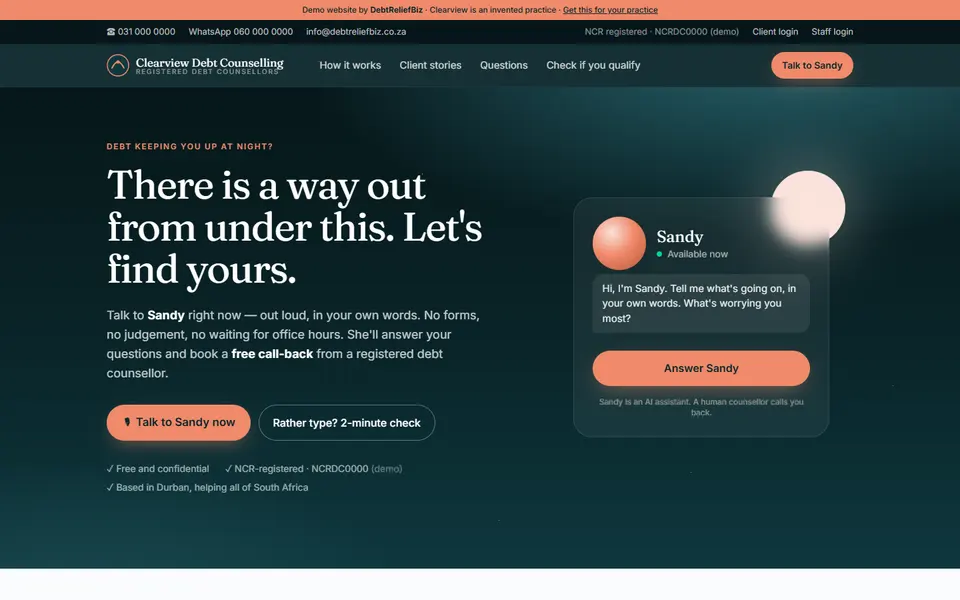
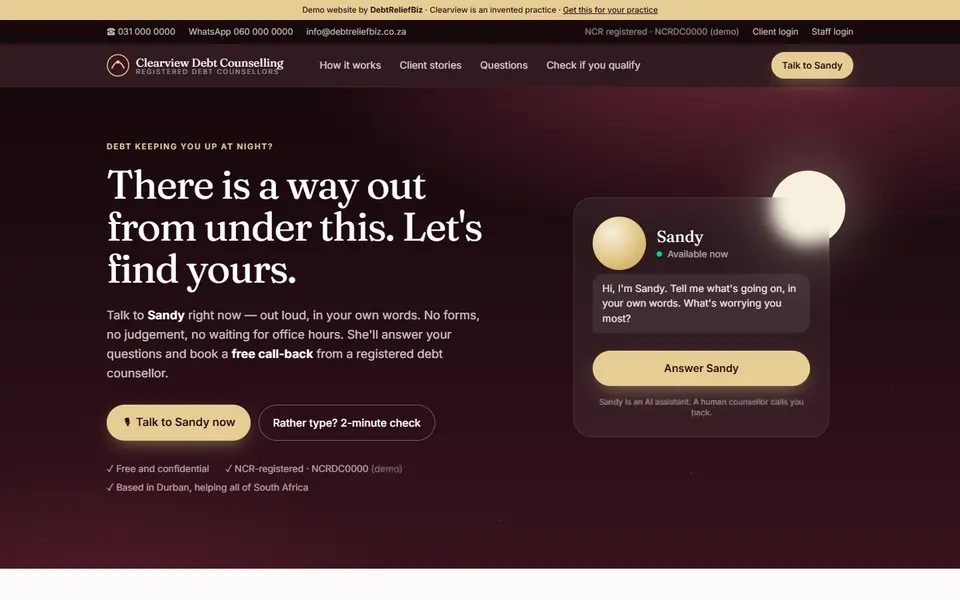
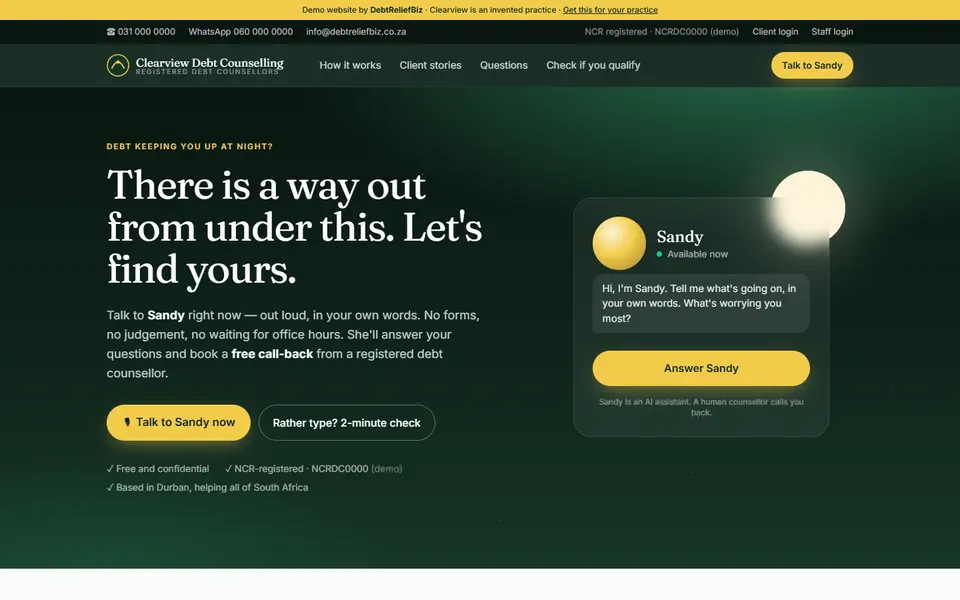
One system, your colours — set from your logo in minutes.